What is a completion test in mine project finance?
What a completion test is in mine project finance, how it differs from an ongoing production covenant, and who certifies the result.
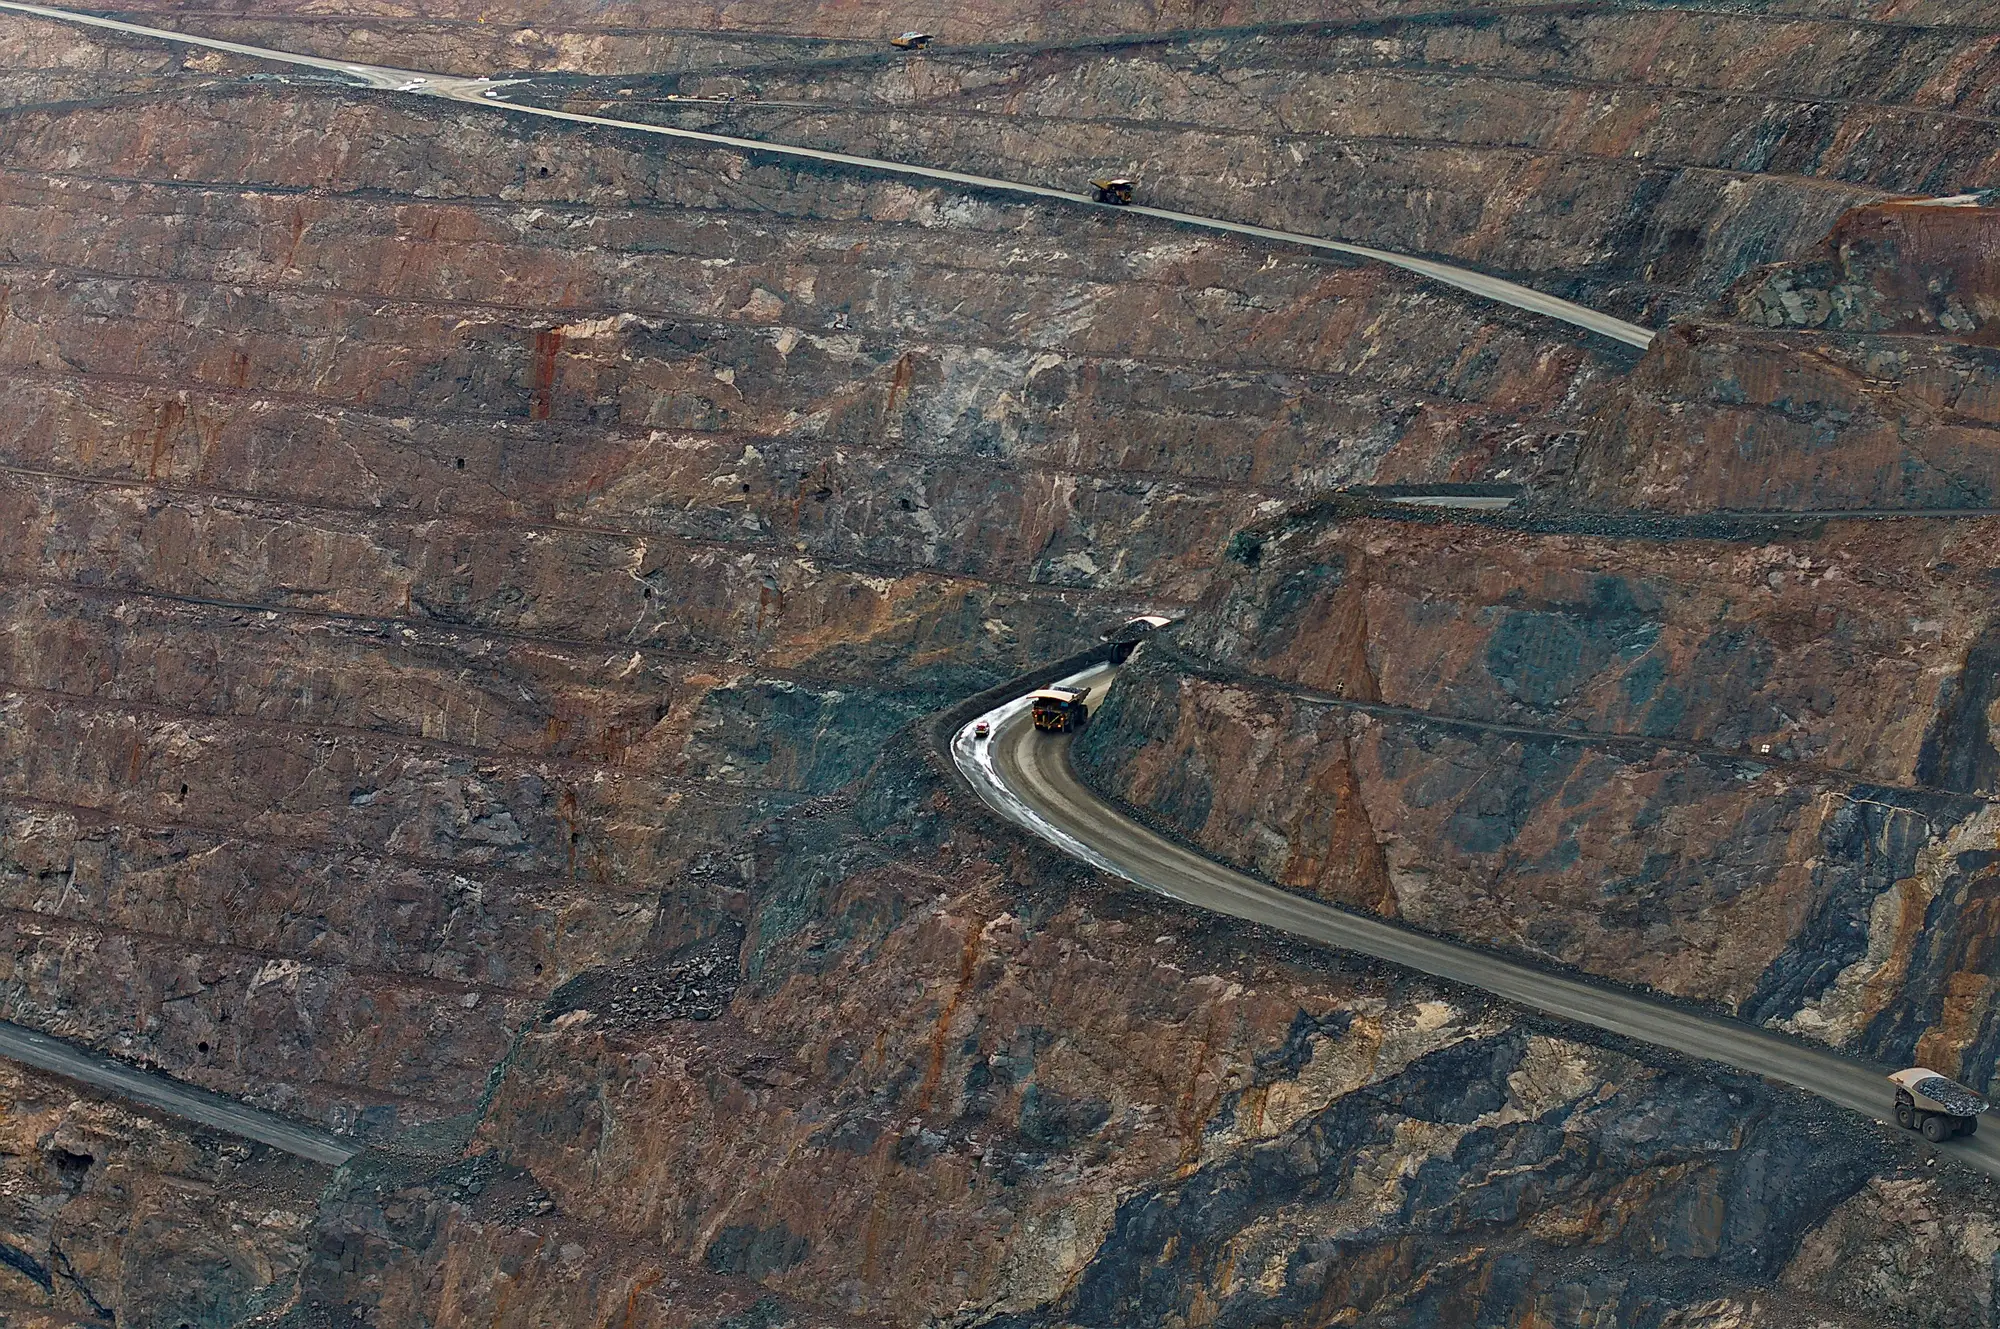
A completion test is the gate a mine project has to clear before a project loan stops being treated as construction risk and starts being treated as operating risk. Until that gate is cleared, lenders are carrying the chance that the pit never ramps up the way the feasibility study said it would. Once it's cleared, the loan converts to its term structure, pricing often steps down, and sponsor completion guarantees typically fall away.
The mechanics are set out in the loan agreement, not in some industry-wide standard, so the specifics vary by deal. But most completion tests share the same shape: the project has to run the plant and the pit at or above a defined percentage of nameplate throughput, usually somewhere in the 70-85% range, for a minimum sustained period, commonly 30 to 90 consecutive days or three consecutive calendar months. Unit operating costs usually have to come in at or under a ceiling tied to the feasibility study. Some facilities add a minimum ore grade or head grade requirement, and almost all of them require the borrower to be current on debt service and free of default during the test window.
How it differs from a production covenant
A completion test is a one-time hurdle. A production covenant is ongoing. Once completion is achieved, most facilities carry forward some version of a minimum production or minimum reserve-life covenant that gets tested every quarter or every year for the life of the loan, usually tied into the debt service coverage ratio or the borrowing base. Miss a completion test and you typically get a cure period, additional equity, or a draw on the sponsor completion guarantee. Miss a production covenant later in the loan's life and the consequence runs toward a cash sweep, a reserve account top-up, or in a bad quarter, a default notice. Both tests ask the same underlying question, whether the pit is moving material at the rate the model assumed, but they sit at different points in the loan's life and carry different remedies.
Who certifies the result
The test result doesn't get certified by the borrower's own mine plan or site reporting. Loan agreements almost universally require an independent engineer, sometimes called the lenders' technical advisor, to review the throughput, grade, and cost data and issue a completion certificate or an opinion letter confirming the test has been met. That's the same independent engineer who signs off on drawdown conditions earlier in construction, confirming that capital spend matches physical progress before the next tranche gets released. The independent engineer's report is the document lenders rely on. Site-reported production numbers feed into it, but the IE's job is to form an independent view, not just restate what the operator submitted.
That's the gap worth naming plainly: the independent engineer is reviewing numbers that, in most deals, originate from the mine's own survey and reconciliation process. There isn't always a second, separately sourced read on how much material actually came out of the pit that month. For a lender or an IE who wants a volume figure that didn't pass through the site's own reporting chain first, Pit Progression builds a monthly extraction number from satellite or aerial stereo imagery, comparing one month's pit elevation surface against the next and converting that difference into a moved-material figure, alongside the two surfaces it was built from.
What happens if the test isn't met on schedule
Missing a completion test deadline doesn't usually mean instant default. Most facilities build in a long-stop date and a series of remedies before that date: extending the test period, injecting sponsor equity to cover a shortfall, or drawing on a completion support agreement or standby letter of credit the sponsor posted at financial close. What changes after a miss is scrutiny. Lenders start asking for more frequent reporting, sometimes monthly instead of quarterly, and the independent engineer's site visits get more frequent too. For a project financier watching that process from outside the fence, having a monthly volume read that doesn't depend on the next scheduled site visit is the difference between finding out about a shortfall at the next IE report and seeing it the month it happens.
If you're tracking a project toward its completion test or a production covenant and want a monthly extraction figure you didn't have to wait on the mine to produce, take a look at what Pit Progression delivers each month.